
Hendrickson Insurance
Plain-spoken insight on Florida insurance — homeowners, auto, flood, condo, and commercial property — plus the operational realities of owning Gulf Coast real estate. Written by Dennis Hendrickson from experience, not theory, for property owners across Sarasota, Bradenton, Venice, Lakewood Ranch, Tampa, St. Petersburg, and Clearwater.
A Charlotte plaza owner with a clean loss history opens a renewal that costs more and pays less. The reason is on the roof, not in the claims file. Here is the hail math and the re-roof math.
Read the full article →
A three million dollar bayfront home on Longboat Key cannot go to Citizens. State law shuts the door at 700,000. Here is what Chubb, PURE and Vault are actually underwriting, and where the house goes when they pass.
Old Dominion non-renewed every property policy on a shopping center I managed. Florida and North Carolina both give you 45 days. Here is what to do with each of them, and why the reason on the letter decides everything.
A slip-and-fall letter from a billboard law firm, and the parking lot video that ended it. Why cameras are the cheapest liability defense for Florida strip center, plaza, and commercial property owners, how to set them up, and what footage does to a premises claim.
If you own multiple homes, cars, boats, jewelry, art, or a business on the Gulf Coast, a standard policy leaves you exposed. How high-net-worth families actually insure: HO5, one consolidated program, Chubb and PURE-style carriers, scheduled valuables, high-limit umbrella, kidnap and ransom, and more.
How much umbrella insurance you actually need in Florida, in plain English. What an umbrella sits on top of, when a Gulf Coast household or business needs one, how to size it to your net worth, and the underlying-limits trap that leaves people exposed.
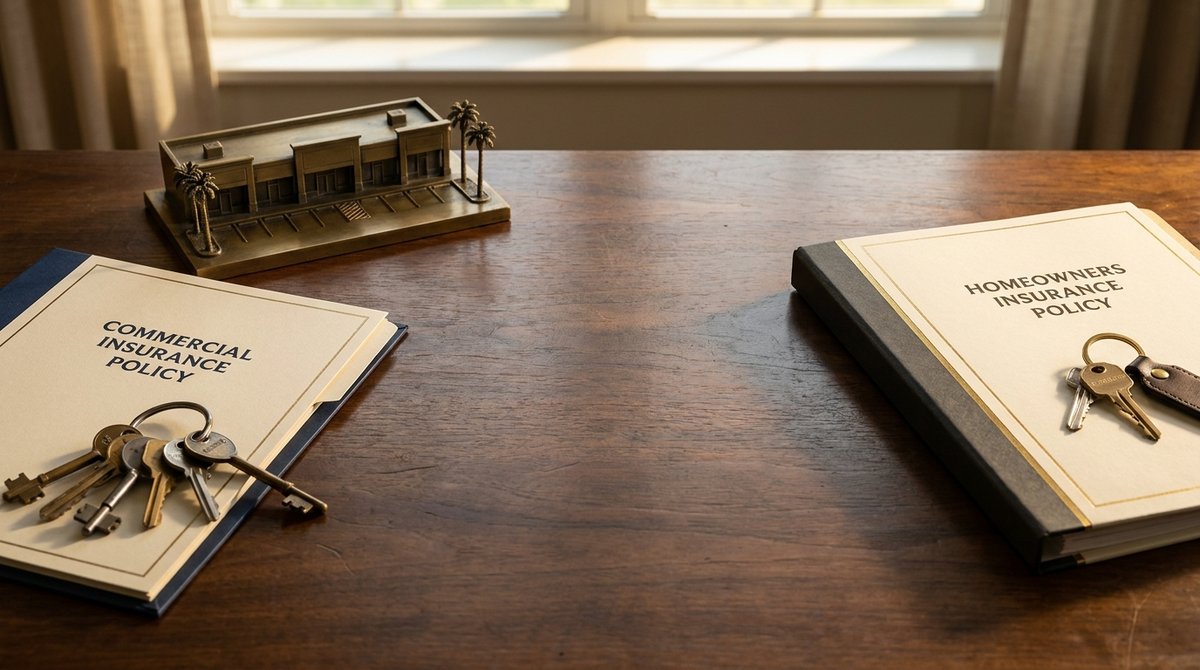
Where your Gulf Coast Florida business insurance ends and your personal insurance begins, claims fall through the seam. The common coverage gaps in Sarasota, Bradenton, Tampa, and St. Petersburg, and how one independent agent for both lines closes them.
A Florida restaurant or bar needs more than general liability. Liquor liability, property, and workers comp are the coverages Gulf Coast owners miss most.
Your Florida homeowners or renters policy may cover a storage unit, but only to a limit. What is actually covered, what is excluded, and how to close the gap.
What surety bonds Florida Gulf Coast contractors actually need, license, bid, performance, and payment, how bonding and Florida Statute 255.05 work, and how a Sarasota insurance agency helps you build bonding capacity.
Florida is a no-fault state, so PIP and property damage are required but not enough. What Sarasota and Gulf Coast drivers actually need from auto insurance.
Dennis Hendrickson changed a New Jersey state tennis rule at 17 and played four years of Division I tennis at UNC Charlotte. Today he writes both the commercial and the personal insurance for Gulf Coast owners himself, and he works a renewal or a claim the way he played: nothing conceded, no point given away.
When you apply, he answers. Every application goes straight to Dennis. He reads it himself and responds the same business day in most cases, always within 48 hours.
Read the story → Start a quote →