
A Charlotte plaza owner who has not filed a property claim in five years opens the renewal and finds three things. The premium went up. The wind and hail deductible changed from a flat dollar amount to a percentage of the building limit. And there is a new page, a roof surfacing schedule, that nobody mentioned when the quote came over.
The owner's first question is always the same: I did not have a claim, so why am I paying for one? The honest answer is that the carrier is not pricing your claims history. It is pricing your roof, and the hail that has been falling on every roof in Mecklenburg County.
I lived in Charlotte for four years and I managed shopping centers before I sold insurance. This is the renewal conversation I have most often with North Carolina plaza owners right now, so here is how it works.
What the underwriter is looking at
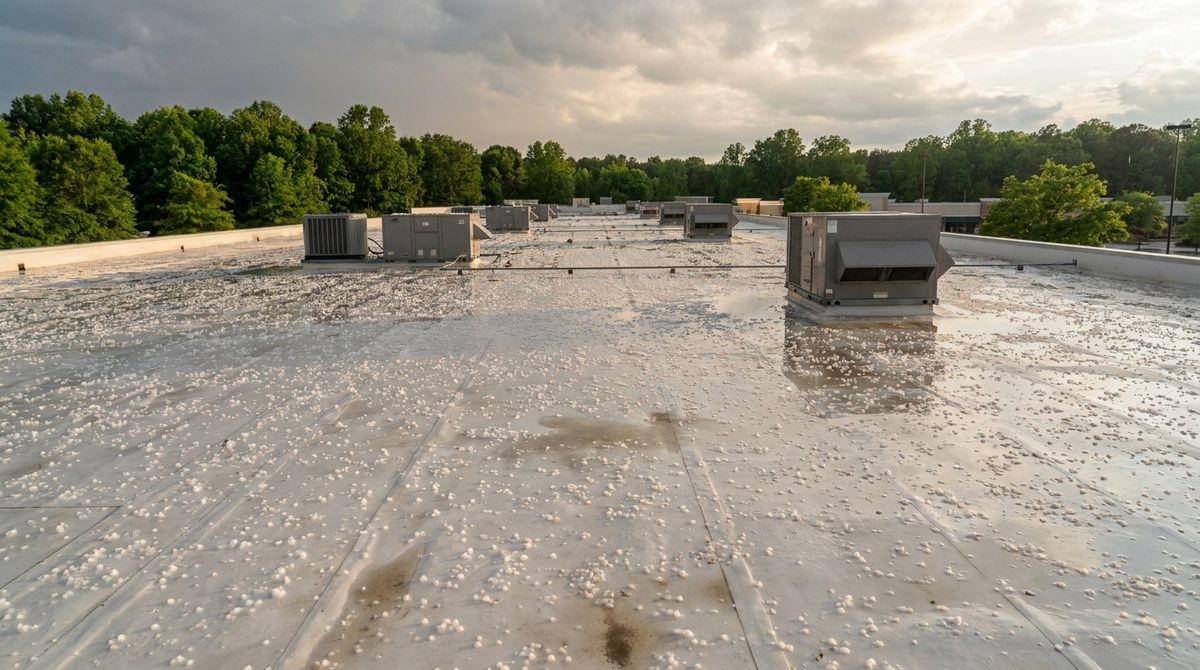
Charlotte does not have a hurricane deductible or a Beach Plan problem. It has hail. NOAA's NEXRAD radar network, compiled through its Severe Weather Data Inventory, has logged repeated hail of an inch or larger in and around Charlotte since the start of 2025, with the largest stone in the city at an inch and a half on June 25, 2025. An inch is the size where a single-ply membrane starts to bruise, metal panels dent, and rooftop units lose their fins.
A carrier does not need your building to have filed a claim to know this. It has the radar data, it has the claims its other insureds filed on the same storm tracks, and it has a book of Charlotte retail roofs that it has been paying for. When a region runs through spring after spring of hail, the whole class gets repriced at renewal, and the clean buildings are in the class.
What changes on your file is not the rate alone. It is the structure of the policy, and the structure is where the money is.
The three changes that cost more than the premium
The percentage deductible. A flat 25,000 dollar deductible becomes 2 percent of the building limit for wind and hail. On a plaza insured at 3 million dollars, that is 60,000 dollars out of pocket per event before the policy pays anything. If two storms hit in one season, that can be two deductibles.
The roof surfacing schedule. This is the one owners miss. The policy still says replacement cost on the building, but the schedule says the roof covering is paid on a depreciation table based on its age. A fourteen-year-old membrane might be paid at half or less of what it costs to replace. Put that together with the percentage deductible and a real hail loss on an older roof can leave the owner carrying most of the replacement.
The cosmetic damage exclusion. Hail that dents a metal roof or standing seam panel without letting water in is excluded as cosmetic. The roof looks like a golf ball, it will fail sooner, the next buyer's inspector will flag it, and the policy owes nothing today.
None of these show up as a line item called premium increase. They show up as coverage that shrank.
Where the roof puts you
In practice, a Charlotte plaza roof falls into one of three markets.
Under ten years, with permits and a documented installer, it places with admitted carriers at replacement cost with a flat deductible. This is the file carriers want.
Ten to fifteen years, it usually stays admitted, but with a 1 to 2 percent wind and hail deductible and often the surfacing schedule.
Past fifteen years, on a building that has been through the recent hail seasons, it often goes to surplus lines. That means a 2 to 5 percent deductible, the roof paid at depreciated value, and a cosmetic exclusion. Surplus lines is not a punishment, and for some buildings it is the right answer for a year or two. But it should be a plan, not a surprise.
If your carrier non-renews instead of repricing, North Carolina General Statute 58-41-20 requires 45 days written notice with the precise reason. On a Charlotte plaza that reason is usually the roof.
The re-roof math
Owners treat a re-roof as a maintenance expense they push to next year. On a plaza in a hail market, it is an insurance decision, and it usually pays better than anything else on the capital plan.
Here is how to run it for your own building. Take the wind and hail deductible you carry now and the one you would carry with a new roof. Take the difference in premium between the surplus lines or scheduled quote and an admitted quote at replacement cost. Then add the gap the surfacing schedule creates on your current roof: what a replacement costs minus what the schedule pays at its age. That last number is what you are self-insuring every spring and never see on the invoice.
A new roof with permits removes the schedule, brings back a flat deductible, and reopens the admitted market. It also shows up on the next appraisal, the next refinance and the next sale. Buyers of Charlotte retail are reading roof ages the same way carriers are.
There is one timing rule that matters. Get the roof done, permitted and closed out before your agent submits the renewal, not after. An underwriter quotes the roof in the file. A roof that is under contract but not finished is still the old roof.
What to put in the file before renewal
Whether you re-roof this year or not, the submission decides the quote. Ninety days before renewal, send your agent:
- The roof age, type and installer, with the permit and final inspection
- Any warranty and the last two roof inspection reports with photos
- Every hail claim or inspection on the building, paid, denied or never filed
- Rooftop unit ages and any curbs or penetrations added since the roof went on
- The rent roll with tenant uses, since a strong tenant file helps the underwriter get comfortable with the rest
Charlotte's tenant side is strong. Colliers put metro retail vacancy around 4 percent in the first quarter of 2026. Underwriters like full centers with paying tenants. The roof is the part of the file the owner controls, and it is the part that moves the price.
The point
A higher renewal with no claim on a Charlotte plaza is not a mistake by the carrier. It is the hail market pricing your roof. Read the deductible and the surfacing schedule before you read the premium, and if the roof is past ten years, run the re-roof numbers before the next spring storm season does it for you.
Get a quote on this coverage.
Ten minutes on the application. Dennis reads it himself and responds the same business day in most cases.
Start the application →Hendrickson Insurance, (941) 952-7991, dennis@hendricksonins.com, FL License E095547.
Coverage descriptions are general. Actual coverage is governed by the terms, conditions, and exclusions of the issued policy. Availability varies by carrier and by state.